S2 Episode 2 — One Salary, Multiple Expenses
Duration: 13:30 minutes
What actually lands in your account after tax — and the habits that stop it disappearing before you’ve made a single decision.
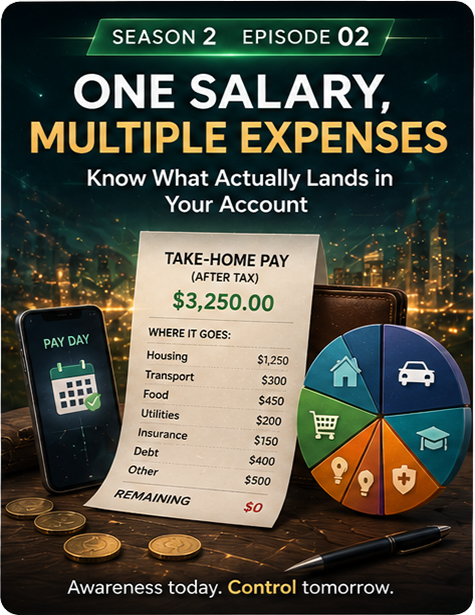
Episode Overview
Duration: 13:30 minutes
Your gross salary is not the number that matters — the number that matters is what actually lands. This episode breaks down what is taken before your salary reaches you (income tax, social contributions, pension, health insurance) and why those rules vary wildly by country. Then it goes further: net salary minus expenses equals what is genuinely yours to work with. I walk through the first foundational habit of this series — a two-phase tracking system that gives you full visibility over your money before you make a single financial decision.
What You’ll Learn
- The real difference between gross salary and net salary — and why it varies so much by country
- Why monthly tax withholding is often just an estimate, not a final number
- How to find your real number using your own payslip and bank statements
- The two-phase tracking habit: short-term visibility and annual-cost visibility
- Why visibility has to come before any decision about saving or investing
Key Takeaways
Your salary is what you keep, not what you earn
Income tax, social contributions, pension, and health insurance are taken before you see the money. The gap between gross and net can be 30–40% depending on where you live — know your real number, not the average.
The monthly deduction is often just a guess
In many countries, what is withheld monthly is an estimate of what you will owe, not the final calculation. The real number is settled at year-end — plan around that uncertainty rather than ignoring it.
Visibility comes before choice
Track everything for two to three months, then go back through twelve months of statements to catch annual costs. Only once you see the full picture can you start making real decisions about what to keep and what to cut.
Episode Summary (click to expand)
An overview of what’s covered in this episode.
In the last episode we set the stage — you are either building on something handed to you or building from zero. Either way, you are at the starting line. This episode looks at the first number that actually matters: not the salary you were offered, but the salary that lands in your account.
Gross vs. Net
Your first payslip arrives, and the number that hits your bank account is smaller than the one in the job offer. Income tax, social security contributions, pension, and health insurance are taken before you ever see the money. The exact amounts vary enormously by country — in some places the gap is brutal, in others it is smaller, but almost everywhere something is taken before it reaches you.
Using a 40,000 gross salary as an example: income tax, social contributions, pension, and health insurance can together take 16,000 — a 40% difference between gross and net. Higher-tax countries tend to bundle in healthcare and education; lower-tax countries shift those costs elsewhere. The total cost is often more similar than people assume — what changes is who sends the invoice.
One detail almost nobody explains: in many countries, monthly tax withholding is just the tax office’s best estimate, divided by twelve. The real calculation happens at year-end, when you either get money back or owe more. The monthly deduction is an estimate, not a verdict.
The Two-Phase Tracking Habit
Once you know your net salary, the next step is tracking what leaves — rent, utilities, food, transport, subscriptions, and the invisible leaks like coffee and small purchases that add up unnoticed.
Phase one: track every expense for two to three months, not one — a single month can lie to you. This reveals your real net salary, your actual monthly expenses by category, and the gap between them — your starting point for everything else.
Phase two: go back through twelve months of bank statements and find the costs that don’t show up monthly — annual insurance, quarterly bills, subscriptions, holidays, tax bills. Divide by twelve and add that to your phase-one baseline. If you haven’t been earning for a full year yet, start phase one now and set a reminder to complete phase two later.
The structure of your salary — gross, taxes, contributions — is set by law and outside your control. But how you spend what is left is entirely your choice. And small, consistent choices compound: saving an extra $150 a month grows to roughly $26,000 over ten years with modest returns — not because of magic, but because of time and consistency.
The next episode covers the emergency fund — the buffer that sits between your salary and the rest of your life, and protects you when things go wrong.