S2 Episode 7 — Inside the Portfolio
Duration: 13:39 minutes
Last episode I sorted your money into three pots and left a question hanging: where do the lines between them actually sit? Today I answer it — and show you that one of the most repeated numbers in investing is not quite what you have been told it is.
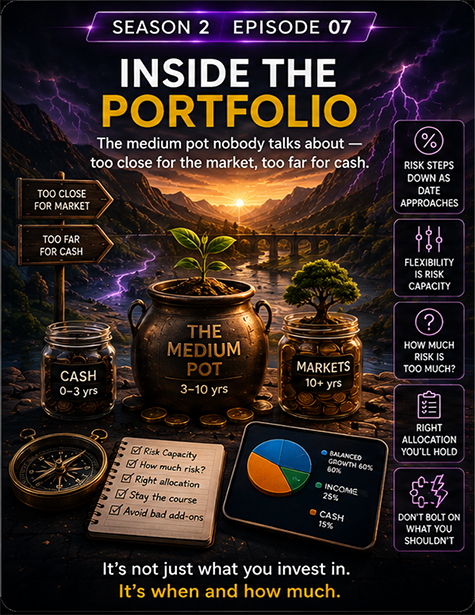
Episode Overview
Duration: 13:39 minutes
In Episode 6 I told you your money has three jobs, sorted by when you need it, and that the long pot can be a single broad global index fund. What I deliberately did not tell you was where the lines between those pots sit, or what the medium pot actually holds. That is this episode. The short pot takes about a minute, because we have already done it. Then we spend the rest of the time on the pot almost nobody talks about — the one where most people at this stage will make their most expensive mistake, in one of two opposite directions. Along the way I take apart a number you have been handed your whole investing life, and show you the difference between a convention and a measurement.
What You’ll Learn
- The two opposite ways people wreck the medium pot — and why the cautious one hides in plain sight
- Why “10 years” is a round number rather than a finding, and what the record actually shows
- The difference between a bond and a bond fund — and why 2022 punished people who confused them
- How to match an instrument to a date instead of guessing at risk tolerance
- The one question that decides your risk capacity, and it is not your age
Key Takeaways
Both directions are expensive
Parked in savings for seven years, inflation quietly removes a sixth of it and nothing ever tells you. Parked in a global equity fund, a fall two years before you buy does not become a paper loss you wait out — it becomes a deposit that no longer exists.
Three and ten are conventions, not measurements
They are rounded in the direction of making investing sound tidier than it is. Under five years equities are a timing bet; ten years is about 95%, not a promise; and somewhere around seventeen to twenty is where the record stops having failures.
Flexibility is risk capacity
What decides how much risk this money can carry is not your age. It is whether the date can move. A soft date can wait out a bad market. A signed completion date cannot — the market does not know about your date and will not be consulted.
Episode Summary (click to expand)
An overview of what’s covered in this episode.
I ended Episode 6 with a question, and I left it open on purpose. Three pots, sorted by when you need the money. The long one can be a single broad global fund, and the safety in your financial life does not have to live inside it, because it already lives in the other two. What I never told you was where the lines between those pots actually sit, or what the middle one holds. That is the whole of this episode.
The Short Pot, in About a Minute
Nought to three years: the emergency fund, plus anything with a near date — next year’s insurance, a course you have already committed to. This money is not invested. Episode 3 covered where it belongs and why, and the rest of this episode assumes it is already in place. That is genuinely all there is to say about it, which is the point: the short pot is boring on purpose.
The Medium Pot, and Two Ways to Wreck It
Three to ten years out: a deposit on a home, a career break, moving country, going back to study, a business you want to start with your own money rather than someone else’s. Real money, with a real date. It is the hardest of the three to get right, because it is too close to be fully exposed to the market and too far away to sit in cash. And people get it wrong in both directions.
The first direction looks responsible. It sits in a savings account for seven years. But at 2.5% inflation, thirty thousand becomes about twenty-five thousand two hundred in today’s money. The number in your account never went down. You simply have sixteen per cent less than you started with, and nothing ever told you. The second direction is worse. It goes into the same global equity fund as the long pot, because that is where the returns are — and then, two years before you plan to buy, the market falls thirty per cent. That is not a paper loss you calmly wait out. That is a deposit that no longer exists, and a purchase that moves back three or four years while you wait for the money to come back.
The Number Everyone Repeats
Three to ten for medium money, ten and beyond for long. It is what you will read, what you will be told, what most calculators assume, and what I have been using all series. I am not going to tell you it is wrong. I am going to tell you what it is: a convention, not a finding. Ten is a round number sitting roughly where the odds get good, and for most purposes good is fine — but a convention and a measurement are different things, and you should know which one you are being handed.
Here is the measurement. Since the Second World War the average American bear market fell about a third and took just under three years for the full round trip. But the average is the least useful number in this episode. Look across a century of them and a third took two years or longer just to break even; the dot-com crash took four. Those are nominal figures, and British data covering a hundred years of bear markets puts the inflation-adjusted recovery more than a year longer than the headline one — what your money actually buys takes longer to come back than the chart suggests. Then there is the tail: Japan’s market peaked in 1989 and took more than thirty years to recover. So when someone tells you three years is enough time to recover from a fall, that is the average talking. You do not get to live in the average. You live in whichever one you get.
At the other end, ten years has been positive around 95% of the time. Genuinely good — but not certainty, and in the last fifty years two of those decades were negative. Twenty years is where it gets clean: no rolling twenty-year period on record has produced a negative total return. So, side by side: the convention says short is 0 to 3, medium is 3 to 10, long is 10 and beyond. The evidence says under five years equities are a timing bet, ten years is 95% rather than a promise, and seventeen to twenty is where the record stops having failures. I will keep using three and ten for the rest of the series, because that is the language everyone else uses and I would rather you could follow any conversation you have about this. But now you know what sits underneath those numbers.
One caveat I owe you, because it usually gets left out. Almost every figure I just gave you is American, and America is the winner — the market that survived and compounded for a century. Japan is the reminder that one country can disappoint you for a generation. That is not an argument against any of this. It is an argument for owning the whole world instead of one country, which is what Episode 6 was about.
What the Medium Pot Actually Holds
In the first few years of that range, with a fixed date, this money is not on the stock market. But that does not mean it has to sit in cash doing nothing, and this is where a lot of advice is lazier than it should be. You have two decent options, and which one you want depends on how firm the date is. If you might need it at any moment, or the date could move around, it is cash or a high-interest savings account — the same place your emergency fund lives, but a different pot.
If you know the date, there is something better: a government bond from a financially solid country, with a maturity that matches when you need the money. Buy a five-year government bond, hold it to the end, and you know today what you will get back and on what day. Interest rates can do whatever they like in between — you still receive the face value at maturity. You have locked in a return instead of accepting whatever your savings account decides to pay you each year, and savings rates get cut quickly when central banks start cutting. Matching the maturity to the date is exactly what large institutions do when they have a bill to pay on a known day. There is no reason you cannot do the same thing.
Three conditions, and they are not optional. First, a bond and a bond fund are not the same thing, and confusing them is how people get hurt. An individual bond has a maturity date. A fund does not — it holds a rolling basket, so when rates rise its price falls and there is no date at which you are made whole again. In 2022, people who had been told bonds were the safe choice watched the broad American bond index have its worst year since it began, and long-dated government bond funds fall 25 to 30 per cent, from the asset class everyone calls safe. For a dated goal you want the bonds, not the funds. Second, hold it to maturity — that is the entire mechanism. Sell early and you are back to whatever the market will pay you that day, which is precisely the risk you were trying to avoid. Third, government does not automatically mean safe; stick to countries with genuinely strong finances, because the eurozone crisis is a reminder that sovereign debt can go badly wrong. One practical note: buying individual bonds directly can involve minimum amounts that do not suit someone putting aside a few hundred a month, and several countries offer retail savings products that do the same job at accessible sizes. It is worth finding out what exists where you are.
At this end of the range you are not trying to grow this money. You are trying to make sure it is there, on the day, in full. Further out — say six or seven years and beyond — you can carry a genuine mix, part still growing and part in something steadier. Series 1 Episode 7 covered asset classes properly if you want the detail. And whatever the mix, it moves one way only as the date approaches: down the risk scale, never up.
The Question That Decides It
What actually decides how much risk you can carry here is not your age. It is whether the date can move. If you want to buy in about seven years and ten would be disappointing but survivable, you can carry real risk — a soft date buys you exactly the extra years the evidence says you need. If you have a signed contract, the completion date is fixed and the money has to be there in March, you can carry almost none, no matter how young you are. Flexibility is risk capacity. A goal with a soft date can wait out a bad market. A goal with a hard date cannot, because the market does not know about your date and will not be consulted. That single question will tell you more than any risk questionnaire ever will.
So, two pots down. Short is boring on purpose and it is not an investment. Medium is where the thinking happens: match the instrument to the date, step down the risk scale as the date approaches and never the other way around. And the numbers everyone repeats are conventions, not measurements — three and ten are useful shorthands, five and twenty are what the record actually says, and now you know both. Next episode, the long pot, which sounds like it should be the simplest of the three, because it is one fund and forty years. It is actually the one where the hardest question lives — not what you should hold, but whether you will still be holding it on the worst day.
Full Transcript (click to expand)
Have you just started earning and want to make sure you are making the right choices? Well then, you are in the right place. Welcome to The Foundation Years, a Beyond PiggyBanks series. I'm Jorge and in each episode we explore simple, practical ways to build your financial foundation before life gets more complicated.
You don't need a financial degree and you don't need a lot of money to begin. You just need the right decisions, made early enough to matter. Let's set the foundation.
In the last episode I left you with a question, and I did it on purpose. I told you how money has three jobs, sorted by when you need it: short, medium and long. I told you the long pot can be a single broad global index fund, and that the safety in your financial life does not need to live inside it, because it already lives in the other two pots.
What I did not tell you was where the lines between those pots actually sit, or what the medium pot holds. That is today. The short pot takes about a minute, because we have already done it. Then we spend the rest of the episode on the pot almost nobody talks about, because it is the one where most people, at your stage, will make their most expensive mistake. And along the way I am going to show you that one of the most repeated numbers in investing is not quite what you have been told it is.
Now the short pot, and quickly because we have already done it. 0 to 3 years: your emergency fund, plus anything with a near date. Next year's insurance, a course you have committed to. This money is not invested. And episode 3 of this series covered where it belongs and why. If you have not heard it, start there, because the rest of this episode assumes it is already in place. And one note before we move on — and I will come back to it properly in a minute — 3 years is the conventional line.
Now the medium pot, 3 to 10 years out. A deposit on a home, a career break, moving country, going back to study, a business you want to start with your own money rather than someone else's. This is real money, with a real date. And it is the hardest of the three to get right: too close to be fully exposed to the market, and too far away to sit in cash.
People get it wrong in both directions. Direction 1: it sits in a savings account for 7 years, because that feels responsible. But at 2.5% inflation, 30,000 becomes about 25,200 in today's money. The number in your account never went down, you just have 16% less than you started with. And nothing ever told you.
Direction 2, and this one is actually worse: it goes into the same global equity fund as the long pot, because that is where the returns are. Then, 2 years before you plan to buy, the market falls 30%. That is not a paper loss you calmly wait out. That is a deposit that no longer exists, and a purchase that moves back 3 or 4 years while you wait for the money to come back.
So the medium pot needs its own answer. And that brings us to the number I promised to come back to: 10 years. 3 to 10 for medium term money, 10 and beyond for long. It is what you will read, what you will be told, and what most calculators assume. It is also what I've been using all series. I'm not going to tell you it is wrong. I'm going to tell you what it is. It is a convention, not a finding. 10 is a round number, sitting roughly where the odds get good, and for most purposes good is fine — but a convention and a measurement are different things, and you should know which one you are being handed.
So here's the measurement. Since the Second World War, the average American bear market fell about a third and took just under 3 years for the full round trip — down, and back to where it started. But the average is the least useful number in this episode. Look across a century of them, and a third took 2 years or longer to break even. The dot-com crash took 4, and those are nominal figures. British data covering 100 years of bear markets puts the inflation-adjusted recovery more than a year longer than the headline one. What your money actually buys takes longer to come back than the chart suggests.
Then there is the tail. Japan's market peaked in 1989, and it took more than 30 years to come back. So when someone tells you 3 years is enough time to recover from a fall, that is the average talking. You do not get to live in the average. You live in whichever one you get.
At the other end, 10 years has been positive around 95% of the time. Genuinely good. Not certainty. And in the last 50 years, 2 of those decades were negative. 20 years is where it gets clean: no rolling 20 year period on record has produced a negative total return.
So, side by side: the convention says short is 0 to 3, medium is 3 to 10, long is 10 and beyond. What the evidence says is, under 5 years, equities are a timing bet. 10 years is 95%, not a promise. 17 to 20 is where the record stops having failures. I am going to keep using 3 and 10 for the rest of this series, because that is the language everyone else uses, and I would rather you be able to follow any other conversation you have about this.
But now you know what sits underneath those numbers. They are rounded in the direction of making investing sound tidier than it is. So: 3 is the earliest you should ever consider market exposure, not a green light. 5 is the point where it becomes reasonable. And 10 is very likely rather than certain. Same vocabulary as everybody else, better understanding of what it's actually worth.
One caveat I owe you, because it is usually left out. Almost every figure I just gave you is American. And America is the winner — the market that survived and compounded for a century. Japan, on the other hand, is a reminder that one country can disappoint you for a generation. That is not an argument against any of this. It is an argument for owning the whole world instead of one country. Which is what episode 6 was all about.
So the shape of the medium pot — and this is direction and not prescription. In the first few years of this range, with a fixed date, this money is not on the stock market. But that does not mean it has to sit in cash doing nothing. And this is where a lot of advice is lazier than it should be. You have two decent options, and which one you want depends on how firm the date is. If you might need it at any moment, or the date could move around, it's cash, or a high interest savings account. Same place your emergency fund lives, but different pot.
But if you know the date, there is something better. A government bond from a financially solid country with a maturity that matches when you need the money. Here is why this works. Buy a 5-year government bond and hold it to the end, and you know, today, what you will get back and on what day. Interest rates can do whatever they want in between. You still receive the face value on maturity. You have locked in a return instead of accepting whatever your savings account decides to pay you each year. And savings rates get cut quickly when central banks start cutting.
Matching the maturity to the date is exactly what large institutions do when they have a bill to pay on a known day. There is no reason you cannot do the same thing. There are three conditions, though, and they are not optional.
First, a bond and a bond fund are not the same thing. And confusing them is how people get hurt. An individual bond has a maturity date. A bond fund does not. It holds a rolling basket. So when rates rise, its price falls. And there is no date at which you are made whole again. In 2022, people who had been told bonds were the safe choice watched bond funds have their worst year in a long, long time. The broad American bond index had its worst year since it began. Long-dated government bond funds fell 25 to 30 percent — from the asset class everyone calls safe. So for a dated goal, you want the bonds, not the funds.
Second, hold it to maturity. That is the entire mechanism. Sell early and you are back to whatever the market will pay you on that day, which is precisely the risk you are trying to avoid. And third, government does not automatically mean safe. Stick to countries with genuinely strong finances. The eurozone crisis is a reminder that sovereign debt can go badly wrong.
And one practical note: buying individual bonds directly can involve minimum amounts that do not suit someone putting aside a few hundred a month. Several countries offer retail saving products that do the same job at accessible sizes. It's worth finding out what exists where you are. Either way, at this end of the range, you are not trying to grow this money. You are trying to make sure it is there, on the day, in full.
Further out, say six or seven years and beyond, you can carry a genuine mix, part still growing and part in something steadier. Series 1 episode 7 covered asset classes properly if you want the detail. And whatever the mix, it moves one way only as the date approaches: down the risk scale, never up.
Now, the thing that actually decides how much risk you can carry here is not your age. It is whether the date can move. If you want to buy in about seven years and ten would be disappointing, but survivable, you can carry real risk. A soft date buys you exactly the extra years the evidence says you need. If you have a signed contract, the completion date is fixed and the money has to be there in March, you can carry almost none, no matter how young you are.
Flexibility is risk capacity. A goal with a soft date can wait out a bad market. A goal with a hard date cannot, because the market does not know about your date and will not be consulted. That single question will tell you more than any risk questionnaire ever will.
So, two pots down. Short is boring on purpose and it is not an investment. Medium is where the thinking happens. Match the instrument to the date. Step down the risk scale as the date approaches and never the other way around. And the numbers everyone repeats are conventions, not measurements. Three and ten are useful shorthands. Five and twenty are what the record actually says.
Now you know both, which puts you ahead of most of the conversations you are going to have about this. Next episode, the long pot, which sounds like it should be the simplest of the three, because it's one fund and forty years. And it's actually the one where the hardest question lives. Not what should I hold — whether you will still be holding it on the worst day. Let's set the foundation.